Walnuts: strong export season and supply concerns
September 15, 2026 at 10:37 AM ,
Der AUDITOR
Noteworthy trends
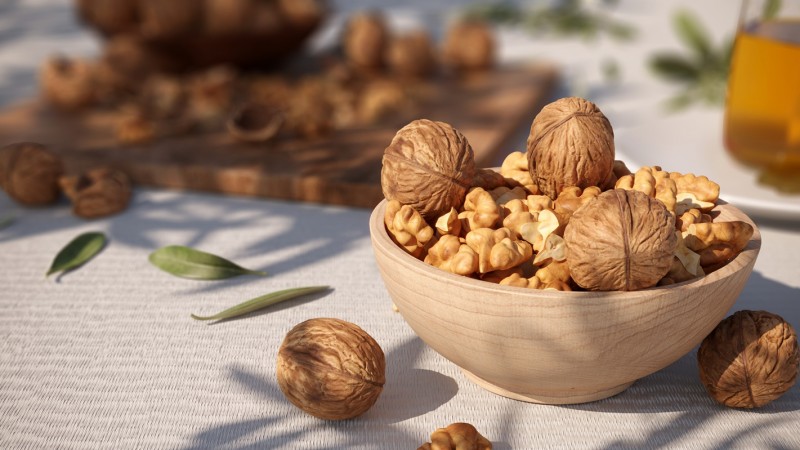
In the Shipment Report for August, the final month of the season, California Walnuts (CWB) switched to short tons and no longer included receipt data. Noteworthy trends in 2025/2026 are that the Middle East and Africa have replaced Europe as top destination for US in-shell walnuts, that in-shell exports are showing a much stronger upward trend than kernels and that August was quite a strong month for kernel shipments.
Middle East/Africa as top destination for inshells
Monthly and year-to-date figures are strong. Monthly in-shell domestic shipments more than tripled to 355 US tons in August as compared with the 74 US tons noted in August last year. Exports also rose by 40%, from 1,311 US tons in August 2025 to 1,839 US tons in August 2026. Total monthly shipments, therefore, climbed by 51%, from 1,385 US tons in August last year to 2,095 US tons in August this year.
Grand total shipments also stand nearly twice as high as in 2024/2025. Domestic shipments have thereby risen by 44%, and exports have more than doubled. Shipments to Turkey as leading destination for US inshells have more than tripled. The United Arab Emirates, Lebanon and Morocco are showing similarly impressive rises. Exports to Algeria and Iraq have even risen ten- and twentyfold. Subtotal shipments to the Middle East and Africa are 316% up at 95,782 US tons as compared with the 23,004 US tons registered in 2024/2025. The region has clearly replaced Europe as top destination.
With a rather moderate rise of 14% Italy has retained its position as second most important destination. By contrast, shipments to Spain and Germany have fallen by 13% and 39% respectively. At 28,227 US tons subtotal shipments to Europe stand 3% lower than the 29,120 tons witnessed in 2024/2025.
India is also sporting a 13% decline. This is the only country from Asia featuring in the top ten. At 19,819 US tons subtotal shipments to Asia range 3% higher than the 19,295 US tons recorded in 2024/2025.
|
US walnut shipments, inshell (short tons) |
|||
|
Destination |
2024/25 |
2025/26 |
Diff. |
|
Turkey |
17,351 |
64,767 |
273.3% |
|
Italy |
16,709 |
19,089 |
14.2% |
|
India |
16,326 |
14,272 |
-12.6% |
|
UAE |
2,091 |
9,356 |
247.4% |
|
USA domestic |
5,386 |
7,735 |
43.6% |
|
Algeria |
556 |
6,349 |
1,041.1% |
|
Spain |
5,040 |
4,367 |
-13.4% |
|
Lebanon |
1,132 |
4,112 |
263.4% |
|
Germany |
6,080 |
3,683 |
-39.4% |
|
Iraq |
175 |
3,546 |
1,929.4% |
|
Morocco |
705 |
3,350 |
374.9% |
|
Others |
6,208 |
13,995 |
125.4% |
|
Export Total |
72,374 |
146,886 |
103.0% |
|
Grand Total |
77,759 |
154,621 |
98.8% |
|
California Walnut Board, 01/09-31/08 |
|||
Europe still leading destination for kernels
Kernel shipments are also up with monthly figures displaying sharp rises. Monthly domestic shipments rose by 45%, from 6,869 US tons in August 2025 to 9,982 US tons in August 2026. At 7.882 US tons monthly exports also stand more than twice as high as the 3,690 US tons noted in August 2025. Total monthly shipments have consequently surged by 69%, from 10,558 US tons in August last year to 17,864 US tons in August this year.
Total kernel shipments are showing more moderate rises. Grand total shipments are 17% up, whereby domestic shipments have climbed by 10% and exports by 22%. With a 34% rise in shipments Germany has remained the leading export destination for US walnut kernels. Spain, the Netherlands and the UK and Italy are also showing gains. With subtotal shipments to Europe reaching 96,060 US tons, 27% up on the 75,769 US tons in 2024/2025, this still is the most important destination for US walnut kernels.
Exports to Japan range 7% higher. Yet, they have dipped by 4% to South Korea. By contrast, Australia is showing a 33% growth. Subtotal shipments to Asia and the Pacific Rim have risen by 8%, from 42,738 US tons in 2024/2025 to 46,048 US tons in 2025/2026.
Exports to Canada have, in addition, risen by 10%. Subtotal shipments to North America have also increased by 10% to 111,833 US tons as opposed to the 101,336 US tons witnessed in 2024/2025 with domestic shipments accounting for the lion’s share.
Israel is the only country from the Middle East and Africa to feature in the top ten. Exports to here have risen by 13%. At 11,150 US tons subtotal shipments to the region have surged by 75% as compared with the 6,367 US tons recorded in 2024/2025.
|
US walnut shipments, kernels (short tons) |
|||
|
Destination |
2024/25 |
2025/26 |
Diff. |
|
USA domestic |
93,585 |
102,726 |
9.8% |
|
Germany |
34,897 |
46,771 |
34.0% |
|
Japan |
17,602 |
18,850 |
7.1% |
|
Spain |
15,143 |
18,057 |
19.2% |
|
Korea |
15,451 |
14,784 |
-4.3% |
|
Netherlands |
8,413 |
10,142 |
20.6% |
|
UK |
9,274 |
9,837 |
6.1% |
|
Canada |
7,309 |
8,033 |
9.9% |
|
Italy |
3,688 |
5,253 |
42.4% |
|
Israel |
3,890 |
4,401 |
13.2% |
|
Australia |
3,498 |
4,645 |
32.8% |
|
Others |
16,706 |
25,183 |
50.7% |
|
Export Total |
135,871 |
165,956 |
22.1% |
|
Grand Total |
229,456 |
268,682 |
17.1% |
|
California Walnut Board, 01/09-31/08 |
|||
Kernel inventories oversold
As The National Nut Grower reports the USDA issued an announcement on 24 August stating the intention to buy USD 30 million worth of California walnuts as based on Section 32 of the 1935 Agriculture Act, which permits the government body to purchase agricultural commodities for nutritional assistance programmes. Previously, the USDA announced a different walnut purchase over USD 15 million meaning that the agency will buy a total of USD 45 million of walnuts in 2026.
Background is that the harvest is starting. At the same time, reducing the carry-in supplies from the 2025 crop is a priority for the new season. Last year’s crop was the second largest in history with this year’s crop only expected to be a bit smaller. According to International Nut and Dried Fruit Council (INC) estimates presented in July the 2025 US crop reached 734,300 mt (809,427 US tons) and the 2026 will only range 6% lower at 689,500 mt (760,044 US tons).
As the Inventory Report for 31 March along with the Shipment Reports for April to August show in-shell inventories are indeed rather high. Yet, kernels appear to be oversold. At 346 million pounds (173,152 US tons) the in-shell inventory stood 72% higher than the 201 million pounds (100,691 US tons) recorded as of 31 March 2025. The kernel inventory, however, only ranged 5% higher at 160 million pounds (79,985 US tons) as compared with the 153 million pounds (76,350 US tons) registered on 31 March 2025. If the accumulated shipments for April to August are taken off these volumes this will leave an estimated in-shell inventory of 289 million pounds (144,680 US tons) and a negative kernel inventory of -49 million pounds (-24,648 US tons).
|
Estimated remaining inventory |
||
|
Date |
Inshell (short tons) |
Kernels (short tons) |
|
As of 31/03/26 |
173,152 |
79,985 |
|
Shipments April-Aug |
28,472 |
104,633 |
|
As of 31/08/26 |
144,680 |
-24,648 |
|
California Walnut Board Inventory Report 31 Mar, |
||
View more
- price charts for nuts, dried fruit and oilseeds and more
View related articles